Are
stock markets predictors of future economic activity?
Christo Luüs

Background
  ccording to the efficient-markets hypothesis (EMH), financial
markets are "informationally efficient". Therefore,
prices on traded assets such as stocks and bonds, reflect
all known information, and it is consequently impossible to
consistently outperform the market by using any information
that the market already knows, except through luck. Information
or news in the EMH is defined as anything that may affect
prices that is unknowable in the present and thus appears
randomly in the future.
Many investors and researchers have disputed
the efficient markets hypothesis on both empirical and theoretical
grounds. Behavioural economists attribute the imperfections
in financial markets to a combination of cognitive biases
such as overconfidence, overreaction, representative bias,
information bias, an inability to use non-linear reasoning,
and various other errors in reasoning and information processing.
The EMH also does not try to answer the question
of whether investors in general have a good idea of the fate
that awaits the real economy, and if so, if their stock trading
activity will reflect this. In short: Is the stock market
in any sense a predictor of future economic activity as measured
by the real gross domestic product (GDP) growth? This question
is especially pertinent in the current environment, with many
analysts and economists fearing another “Great Depression”
in the USA and other developed economies, while others believe
that the recessionary conditions will start to dissipate towards
the end of 2009 and into 2010. The drop in stock market prices
had been quite severe in the final quarter of 2008, but towards
the end of the first quarter of 2009, markets have shown some
tentative signs of recovery. What implications are there then
for the economies, if any?
The question of whether the stock market
can predict the economy has been widely debated. Those who
support the market’s predictive ability argue that the
stock market is forward-looking, and current prices reflect
the future earnings potential, or profitability, of companies.
Since stock prices reflect expectations about profitability
and since profitability is directly linked to economic activity,
fluctuations in stock prices are thought to lead the direction
of the economy. If the economy is expected to enter into a
recession, for example, the stock market will anticipate this
by bidding down the prices of stocks.
The "wealth effect" is also regarded
as support for the stock market’s predictive ability.
Pearce (1983) argues that since fluctuations in stock prices
have a direct effect on aggregate spending, the economy can
be predicted from the stock market. When the stock market
is rising, investors’ wealth increase and they spend
more. As a result, the economy expands. On the other hand,
if stock prices are declining, investors experience a decrease
in wealth levels and spend less. This results in slower economic
growth.
Problem statement
and method of analysis
Data for the past three and a half decades
were used to determine whether there had been any statistically
significant relationship between the stock market and real
GDP growth. The number of periods (quarters) into the future
that this relationship appeared to be the strongest, was also
determined. A number of stock market indicators were correlated
with the GDP to ascertain which one had the best predictive
power. Finally, apart from the South African experience, these
correlations in other markets were also measured. These markets
included the USA, UK, Germany and Japan.
IMF quarterly data for real GDP in local
currencies were used. Inflation rates were approximated by
the GDP deflators, and share prices were deflated by these
series to obtain share prices in real terms. Stock market
data were obtained from the various bourses, and earnings
growth indices were calculated from PE-ratios and price index
data. Al these series were averaged to quarterly data.
Cross-correlation matrices were compiled
for each of the following stock market variables and the GDP
growth numbers, for the period 1Q1973 to 4Q2008:
- PE-ratio
- Dividend yield
- Year-on-year change in real stock price index
- Year-on-year change in nominal earnings growth index
For South Africa, these four variables were
plotted together with the real GDP growth rates, and are shown
in figure 1.
Casual observation of the plots does not
reveal a lot of information about the strength of correlation
between the data series pairs or lag structures involved.
However, in some of the graphs it would appear that peaks
and bottoms in the equity market were followed by similar
peaks and bottoms in economic growth.
Figure 1: Plots of data series pairs
for SA

Correlation results
The graphs in figure 2 show the correlation
results for lags of 0 to 8 quarters for the four different
stock market indicators and real GDP growth. GDP growth, lagged
on the PE ratio, showed a correlation coefficient of 0.2894
after three quarters, implying a fairly weak predictive power
of the PE ratio on future economic growth. The other popular
valuation measure – the dividend yield – delivered
a similar result, with a correlation coefficient value of
-0.2665 after four quarters. The negative sign is explained
by the fact that dividend and earnings yields rise when stock
markets become bearish (usually as a result of falling share
prices), and fall when markets turn bullish.
Earnings growth showed a relatively strong correlation with
GDP growth, but not much in the way of predictive ability.
In fact, looking at the bottom right graph in fig 1, it would
appear that GDP growth has a much bigger impact on earnings
growth after one or two quarters. This could be explained
by the fact that company results (earnings growth numbers)
are usually reflective of business activity levels that prevailed
one or two quarters ago.
Real share price movements appeared to have
the best predictive ability on GDP growth, and to lead changes
in economic activity by between two and four quarters. The
correlation coefficient(1) of a three
quarter lag was calculated at 0.4509.
Figure 2: Cross Correlation Graphs:
South Africa

Correlation results
in other markets
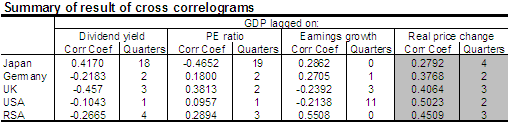
Correlation coefficients for Japan suggested
that stock market indicators were not at all good indicators
for future economic growth, and dividend yields and PE-ratios
had the wrong signs. Real price changes did show a relatively
small positive correlation, with a four quarter lag delivering
the highest correlation. For the other countries, real price
changes also proved to be the best predictors of future economic
activity, with results for the USA coming out top, followed
by the UK and Germany.
Table 1:
Conclusions and
implications
The South African stock market indicators
appear to be much more robust in terms of their predictive
capabilities of future GDP growth than those of the British,
German and Japanese markets. Real share price movements have
given the best correlation results with GDP growth rates in
all markets, with the US coming out the highest and Japan
the lowest. GDP growth lagged share price movements by between
2 to 4 months.
One should keep in mind that even if two
data series are correlated to a lesser or greater degree,
this does not imply causality. Thus, the fact that certain
stock market indicators display a statistically significant
correlation with future GDP growth, does not imply that stock
price changes will determine GDP growth.
Nevertheless, the strength of the downward
correction in share prices that took place between the middle
of 2008 and the first quarter of 2009, provide a rough guide
as to the possible duration of the expected recession. If
the stock market improvements that started towards the end
of the first quarter of 2009 can be further sustained, it
may be an indication that economic activity levels could indeed
start to improve towards the end of 2009 / beginning of 2010.
(1) The correlation coefficient indicates
the strength and direction of a linear relationship between
two variables. A correlation coefficient of -1 indicates
a perfect negative correlation, and 1 a perfect positive
correlation. 0 indicates no linear relationship between
two variables.
|


